The Edge Blog · April 17, 2025 · 3 min read
How I Turned My Tax Refund Into My First Home (And You Could Too)
Now that tax season’s wrapped up, you might be staring at a nice little refund in your bank account. Back in 2013, that exact scenario played out for me—and instead of splurging on a weekend getaway, I used every penny to buy my first…
 Dan SchriverCENTURY 21 Edge
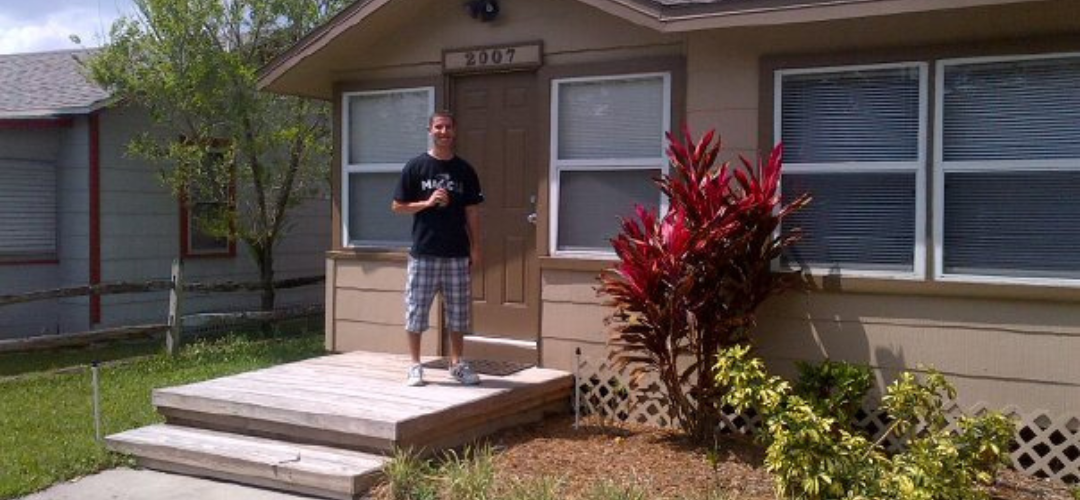
Now that tax season’s wrapped up, you might be staring at a nice little refund in your bank account. Back in 2013, that exact scenario played out for me—and instead of splurging on a weekend getaway, I used every penny to buy my first home. Here’s how it worked, and how yours can do the same. (Also, how awesome are those plaid shorts?!)
My 2013 Tax‑Refund Playbook
When I saw my refund hit my checking account, it felt like a bonus I hadn’t counted on. I topped up my savings just enough to cover the down payment and closing costs, and suddenly I went from renter to proud homeowner. Not gonna lie: it was a huge confidence boost. I even splurged and got guacamole on my Chipotle burrito that night.
Why Your Refund Matters More Than You Think
- Low Down‑Payment Options: You don’t need 20% down. FHA loans start as low as 3.5%, and Florida has local down‑payment assistance programs that get you even closer to zero.
- USDA Zero‑Down Loans: In many qualifying rural areas—like parts of Mount Dora or Davenport—you can get a USDA loan with no down payment. Your refund could then go straight toward closing costs instead of sitting idle.
- Covering Extras: Inspections, appraisals, title fees—they all add up. A refund can wipe out those out‑of‑pocket costs.
- Rent vs. Mortgage: In many markets you’re already paying what a mortgage would be. Why not put that same cash toward building equity?
The Bonus Nobody Talks About: Appreciation
That little home I snagged in 2013 for $117,500 is now worth well over $400,000—talk about a return! If I’d known about cash‑out refinances back then, I could’ve tapped into that equity, held onto the house as an investment, and still used the proceeds to buy our current home. Shoulda, coulda…but everything happens for a reason.
Simple Steps to Put That Refund to Work
- Check Your Numbers
- Review how much your refund actually is after taxes and any withholdings.
- Talk to a Lender
- Find out what loan programs you qualify for—FHA, USDA zero‑down, or local assistance—and what closing‑cost programs exist in your county.
- Budget for Closing Costs
- Ask for a Loan Estimate early so you know exactly what fees you’ll owe at closing.
- Lock In Your Plan
- Once you’ve got your lender’s thumbs‑up, set aside your refund money (and maybe a little extra for move‑in expenses).
Your Next Move
If you’ve been daydreaming about homeownership but felt stuck on saving for that upfront cash—or you wish you’d tapped your home equity sooner—your refund could be the nudge you need. I’m here to walk you through local programs, crunch the numbers, or even just chat about what buying a home in Central Florida looks like today.
Ready to see if your refund can turn into your front‑door key? Shoot me a message or give me a call—I’ve been there, and I’ve got your back.
Looking for More Information?
Reach out anytime. My phone number is (407) 512-8239, or swing by my website. Don't miss out on enhancing your real estate journey with my App.
Dan SchriverCENTURY 21 EdgeWork with Dan